
Why Tap-To-Pay Is Rewriting Point-Of-Sale For Small Teams
When Any Phone Can Be A Terminal, The Question Is No Longer How To Accept Payments But What To Do With The Data.
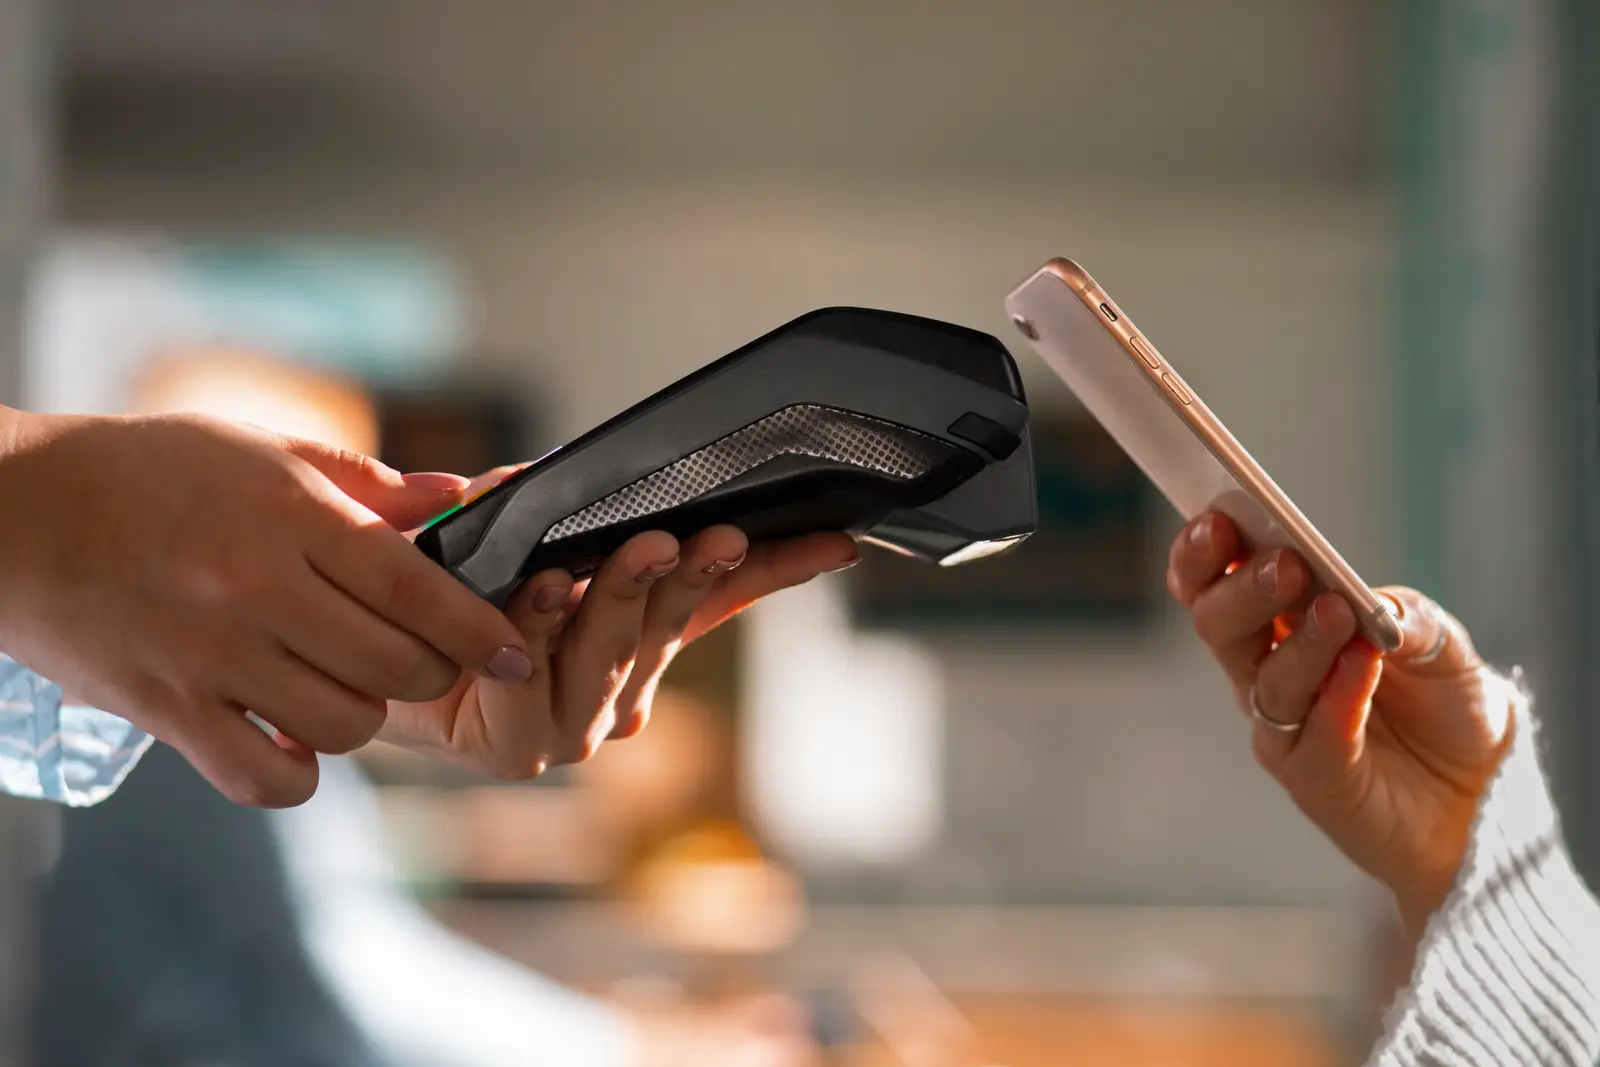
Contactless acceptance on ordinary smartphones removes the last piece of dedicated hardware from the counter. For small teams this is more than a cost saving; it is the moment payments stop being a separate system and become part of the same platform as inventory, payroll and cash planning.
What Changes At The Counter
Staff take payment wherever the customer happens to be standing, receipts are digital by default and the transaction lands in the ledger already categorised. The queue at a fixed till disappears, and a pop-up stall or a delivery driver has exactly the same capability as the flagship store.
Benefits Beyond The Hardware
- No terminal rental, repair or replacement cycle, and no waiting for a courier when a device fails on a Saturday.
- New locations and pop-ups go live in minutes because the only setup step is signing into the app on a phone the team already owns, which makes seasonal markets and one-day events viable in a way they never were with leased hardware.
- Sales data arrives in real time rather than in an end-of-day batch, so stock and cash decisions can be made during trading hours.
Getting Started
- Confirm your devices support NFC and the latest operating system version, then enrol each one from the admin dashboard so lost phones can be revoked remotely.
- Connect the acceptance app to your accounting platform so settlements reconcile automatically against orders and fees are booked to the right account without manual entries.
The Bigger Picture
Payments used to be a cost centre that finance tolerated and operations worked around. That framing no longer holds.
Once every sale flows through the same platform as everything else, payment data becomes one of the richest sources of operating insight a small business has: which hours are busiest, which products sell together, which locations are quietly underperforming. The phone in a staff member's pocket is now both the till and the analyst.
More Related Blogs
Questions? We’re Here To Help.
Most teams are fully onboarded in under a day. Card issuing, ERP sync and approval workflows are configured from a guided two-minute setup, no engineering work required.
No. You can start with a Fexiva account and cards on day one. Bank and ERP connections are optional and can be added at any time from Settings.
Yes. Upgrade, downgrade or cancel from your billing page whenever you like. Changes take effect at the start of the next billing cycle.
All data is encrypted in transit and at rest, access is protected with two-factor authentication and every action is logged in a tamper-proof audit trail.
Yes. Hold balances in 75+ currencies, pay suppliers locally and see consolidated reporting in your home currency.
Fexiva syncs natively with popular accounting, ERP and payroll tools, and connects to 100+ other apps through its open API.
Yes. Upload a CSV or connect your old provider and we will migrate card holders, limits and historical transactions for you.
Enterprise and Business plans include a dedicated onboarding specialist who configures approval workflows and trains your team.
Yes. Fexiva is PCI DSS Level 1 certified and audited annually for SOC 2 Type II. Reports are available on request.
Data is stored in regional data centres in the EU and US. You choose the region when you create your workspace.
Role-based permissions let you decide who can issue cards, approve spend and view reports, down to the team or cost centre.